PROJECT GREENSHANK
STRICTLY PRIVATE & CONFIDENTIAL
MARCHMONT CORPORATE FINANCE
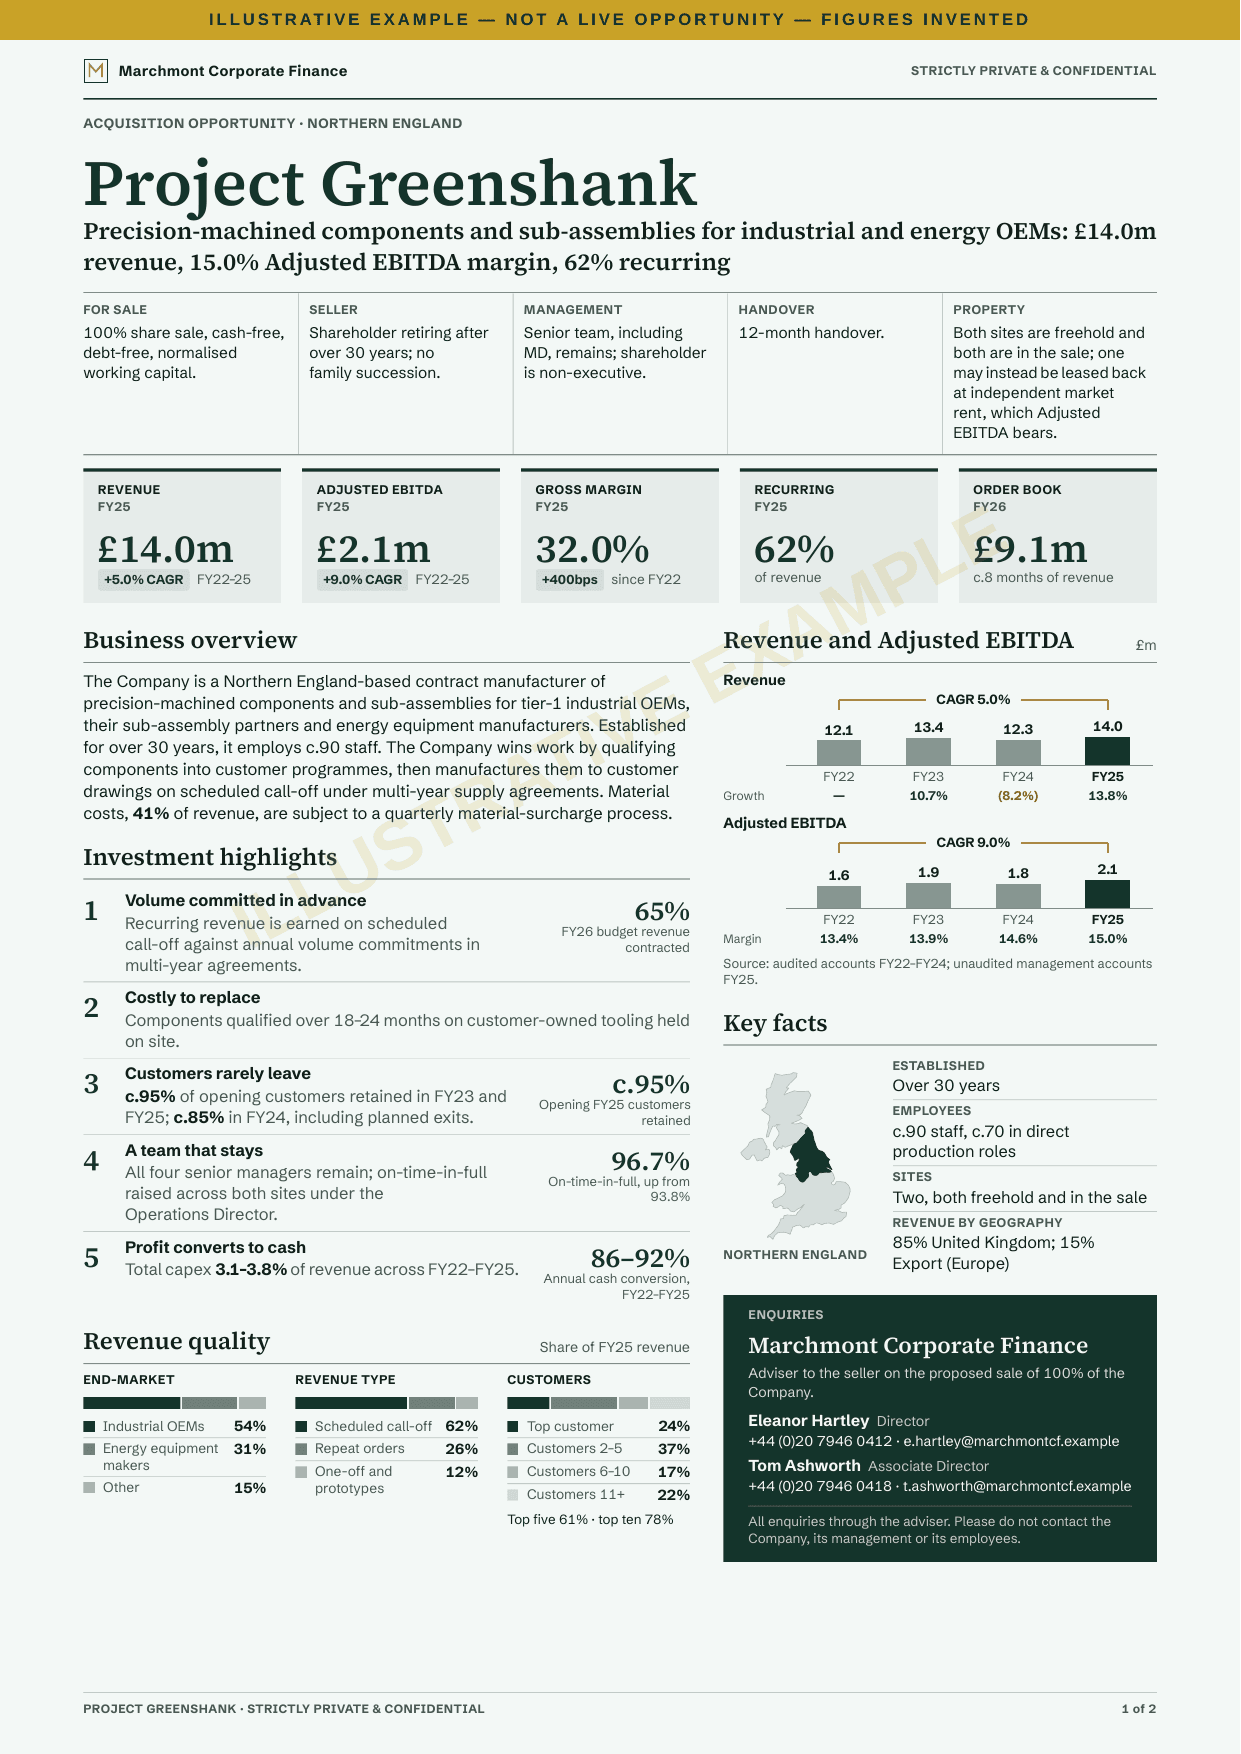
Northern England precision engineering business serving industrial and energy OEMs, with 62% recurring revenue and management staying
Precision-machined components and sub-assemblies for industrial and energy OEMs: £14.0m revenue, 15.0% Adjusted EBITDA margin, 62% recurring
Adviser to the seller on the proposed sale of 100% of the Company.
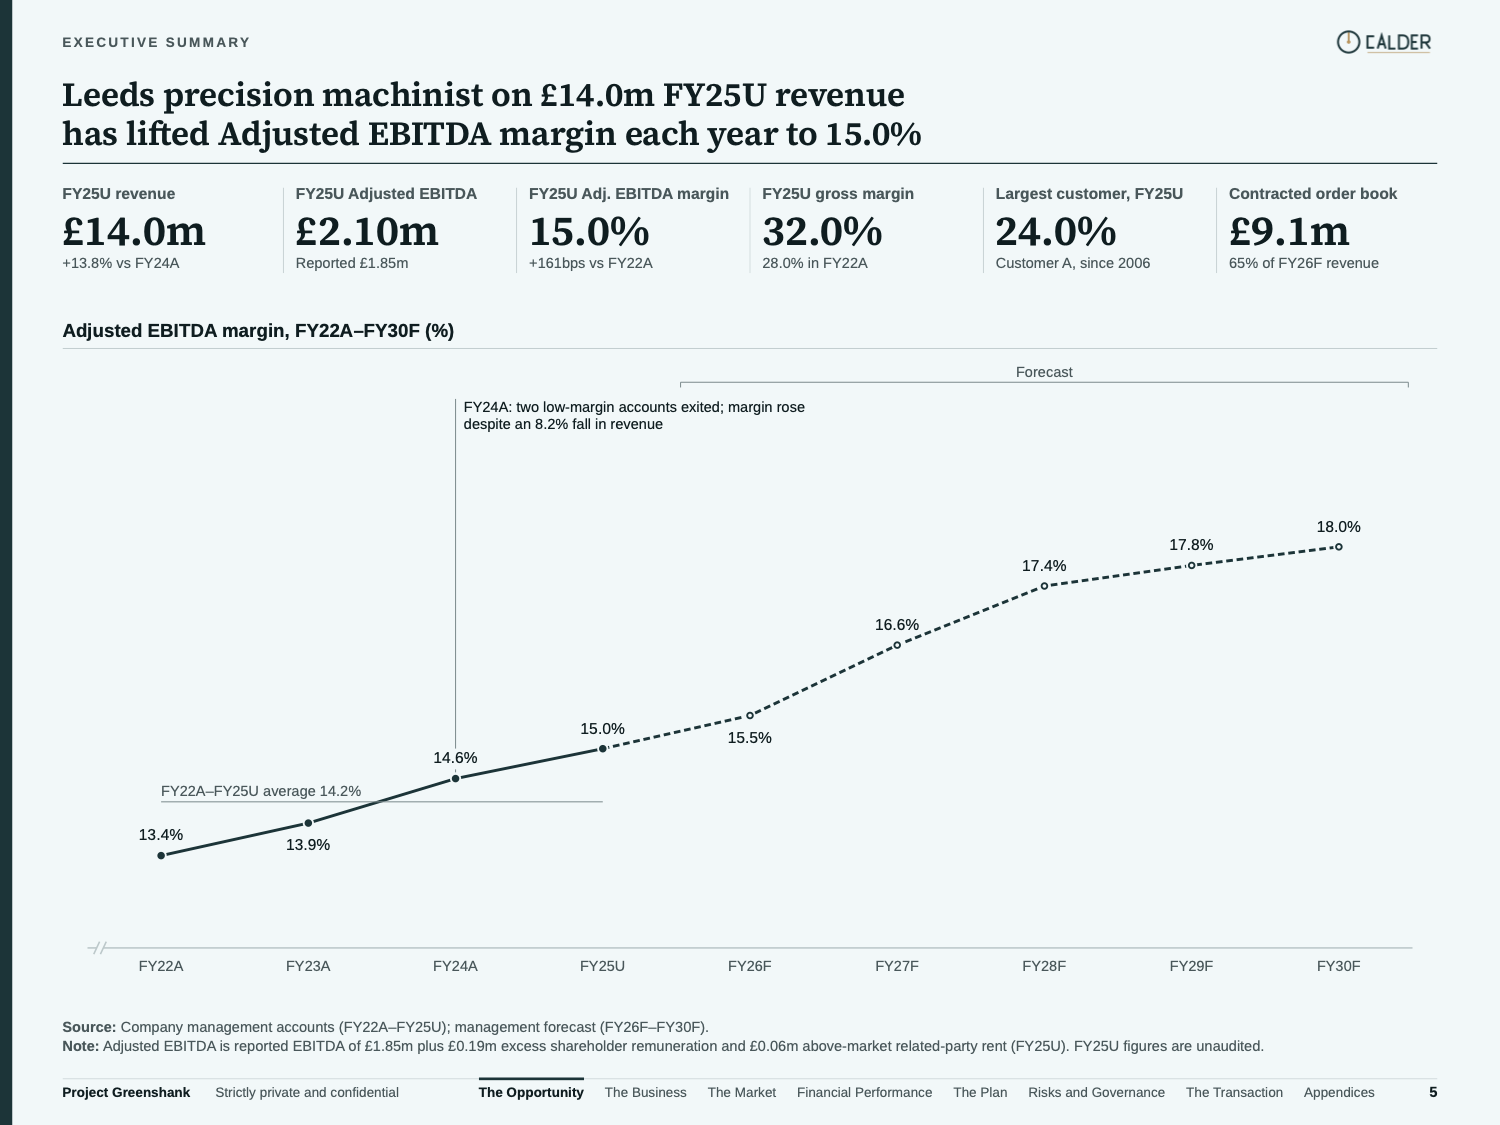
- £14.0m+5.0% CAGRFY22–25
- REVENUE FY25
- £2.1m+9.0% CAGRFY22–25
- ADJUSTED EBITDA FY25
- 32.0%+400bpssince FY22
- GROSS MARGIN FY25
- 62%of revenue
- RECURRING FY25
- £9.1mc.8 months of revenue
- ORDER BOOK FY26
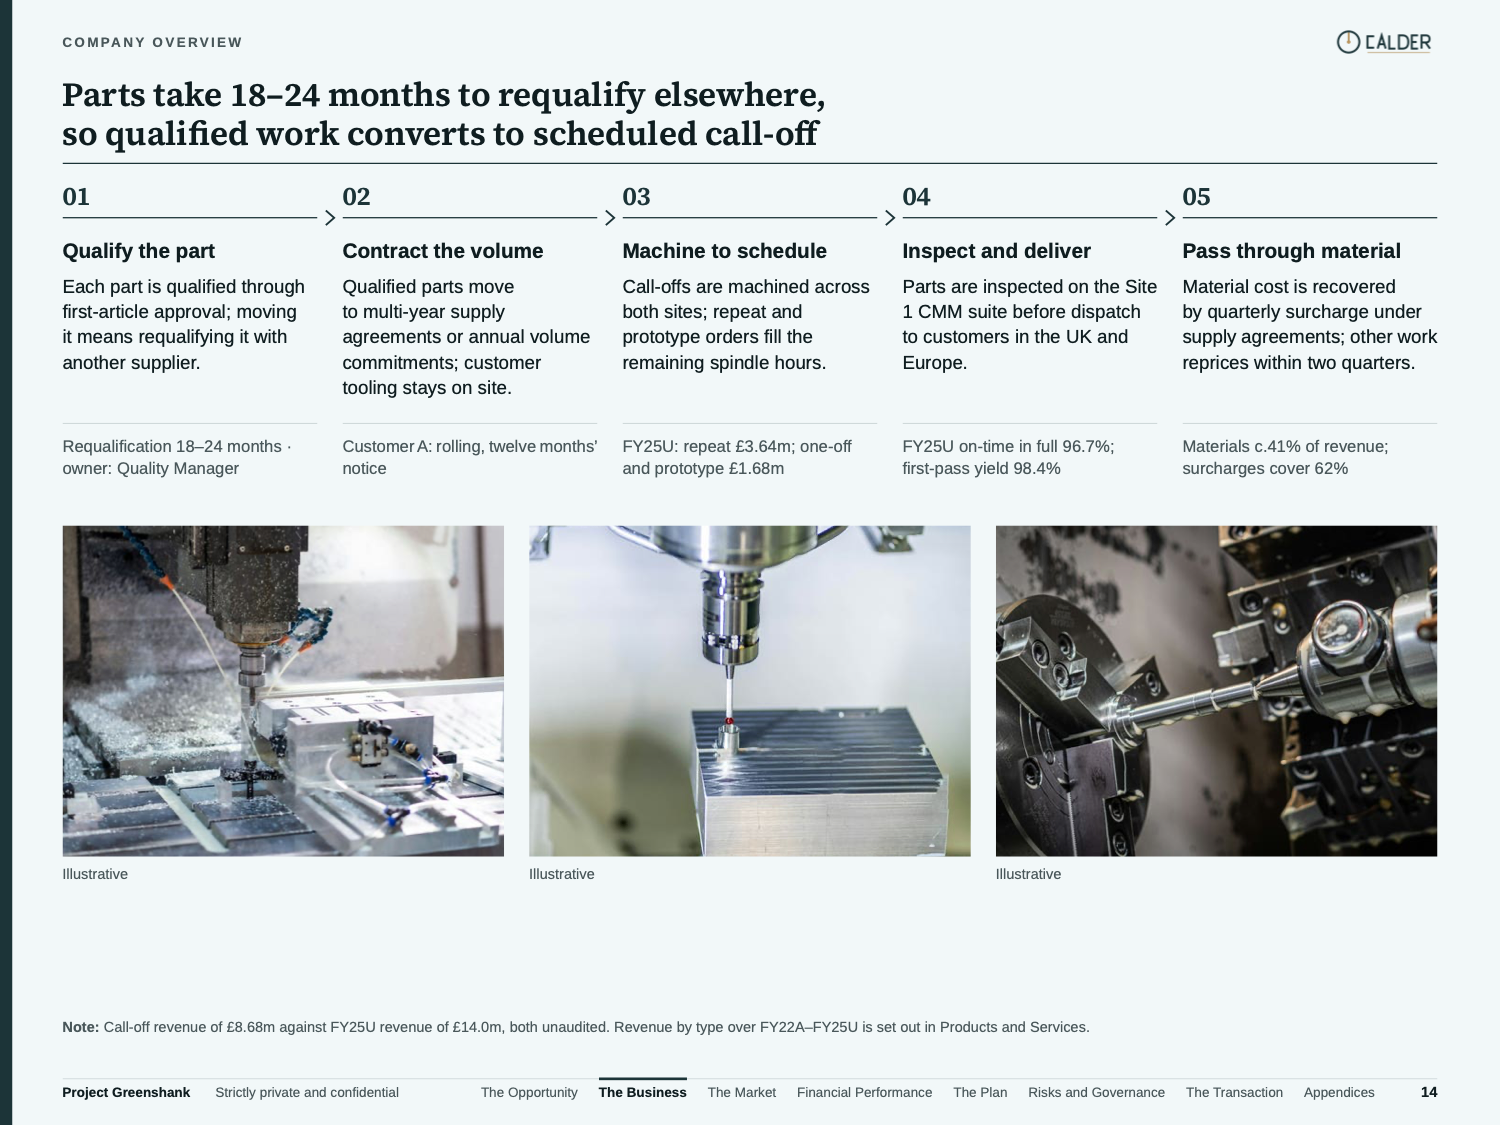
The Company is a Northern England-based contract manufacturer of precision-machined components and sub-assemblies for tier-1 industrial OEMs, their sub-assembly partners and energy equipment manufacturers. Established for over 30 years, it employs c.90 staff. The Company wins work by qualifying components into customer programmes, then manufactures them to customer drawings on scheduled call-off under multi-year supply agreements. Material costs, 41% of revenue, are subject to a quarterly material-surcharge process.
- SECTOR
- Precision engineering and sub-assembly manufacturer serving industrial and energy OEMs
- LOCATION
- Northern England
- REGION
- Northern England
- ESTABLISHED
- Over 30 years
- EMPLOYEES
- c.90 staff, c.70 in direct production roles
- SITES
- Two, both freehold and in the sale
- REVENUE BY GEOGRAPHY
- 85% United Kingdom; 15% Export (Europe)
- FINANCIAL YEARS
- years to 31 March
Revenue quality
Share of FY25 revenue
End-market
- Industrial OEMs
- 54%
- Energy equipment makers
- 31%
- Other
- 15%
Revenue type
- Scheduled call-off
- 62%
- Repeat orders
- 26%
- One-off and prototypes
- 12%
Customers
- Top customer
- 24%
- Customers 2–5
- 37%
- Customers 6–10
- 17%
- Customers 11+
- 22%
Top five 61% · top ten 78%
Investment highlights
Volume committed in advance
Recurring revenue is earned on scheduled call-off against annual volume commitments in multi-year agreements.
65%FY26 budget revenue contracted
Costly to replace
Components qualified over 18–24 months on customer-owned tooling held on site.
Over 15 yearsLongest customer relationship
Customers rarely leave
c.95% of opening customers retained in FY23 and FY25; c.85% in FY24, including planned exits.
c.95%Opening FY25 customers retained
A team that stays
All four senior managers remain; on-time-in-full raised across both sites under the Operations Director.
96.7%On-time-in-full, up from 93.8%
Profit converts to cash
Total capex 3.1–3.8% of revenue across FY22–FY25.
86–92%Annual cash conversion, FY22–FY25
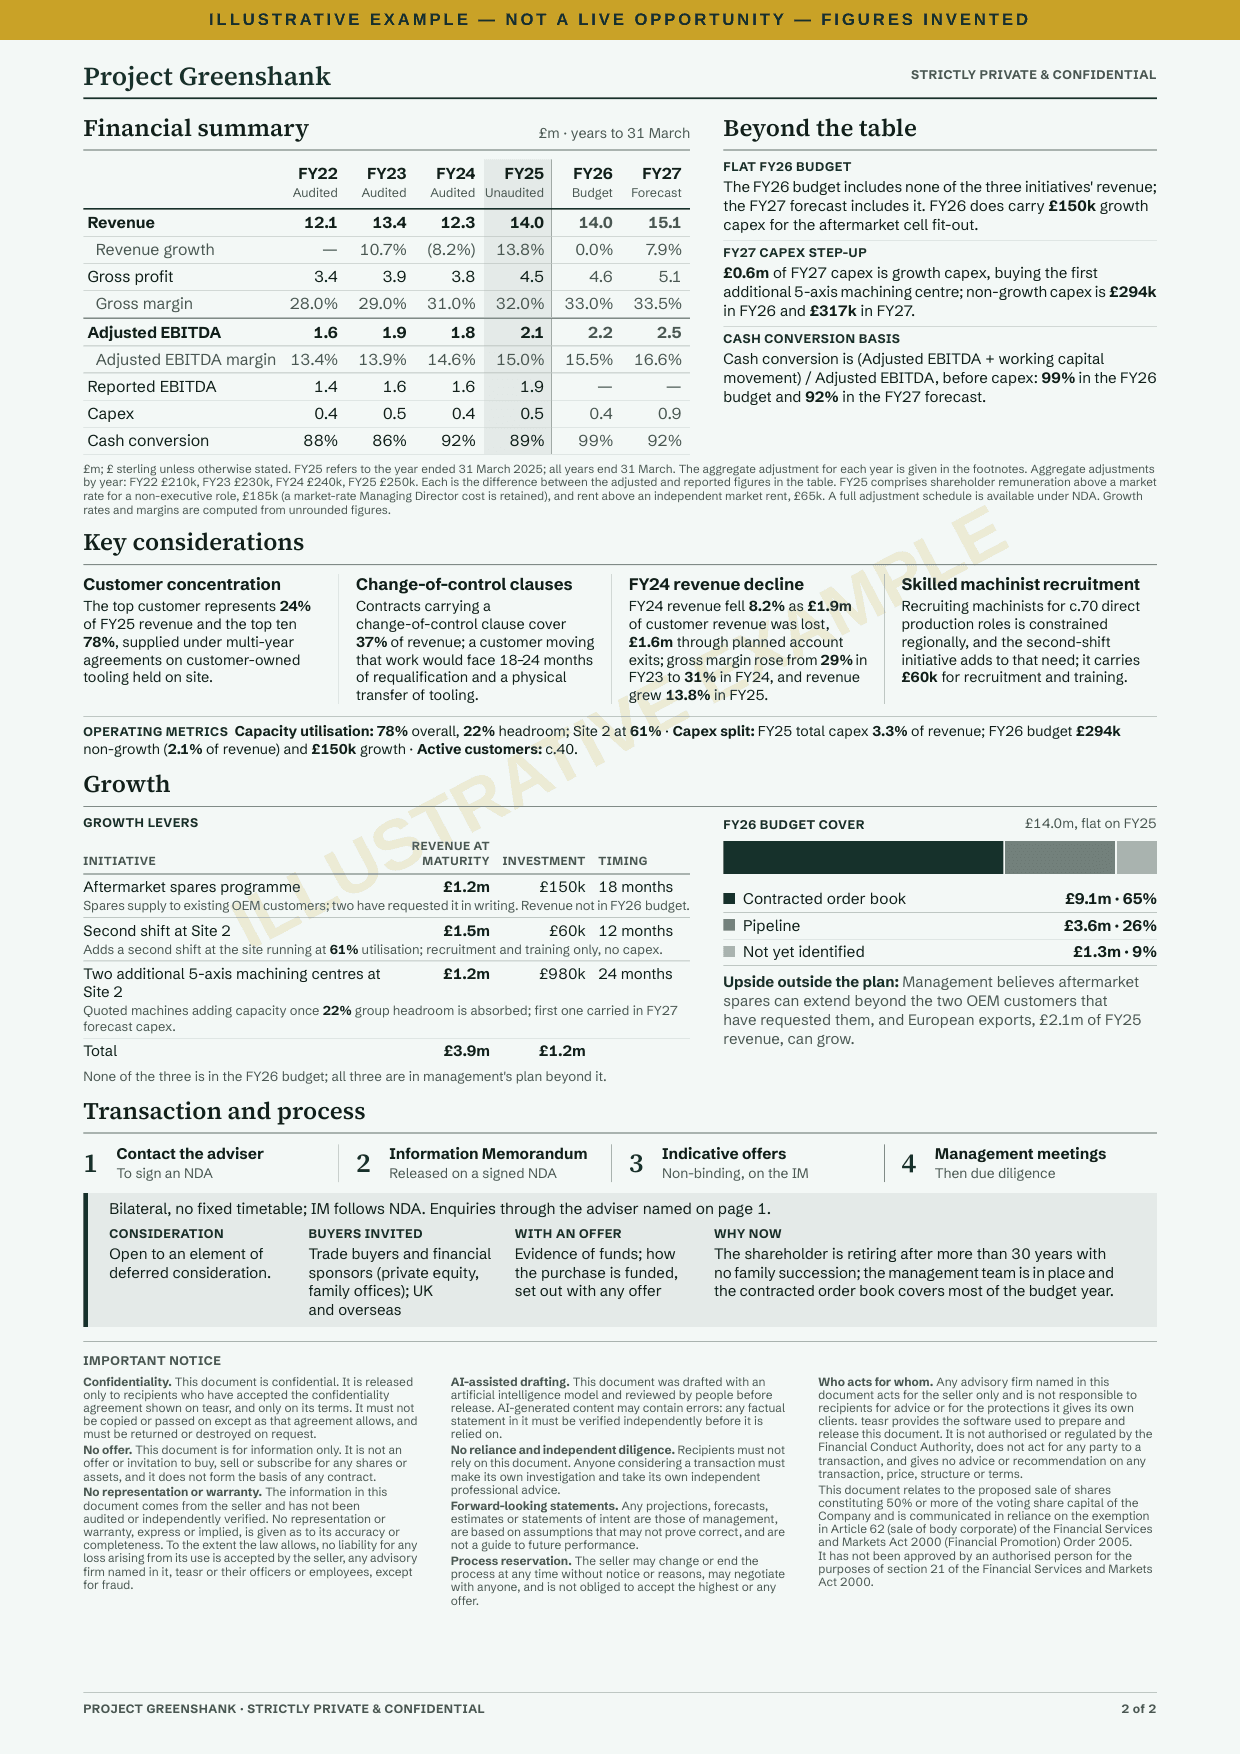
Financial summary
£ in millions
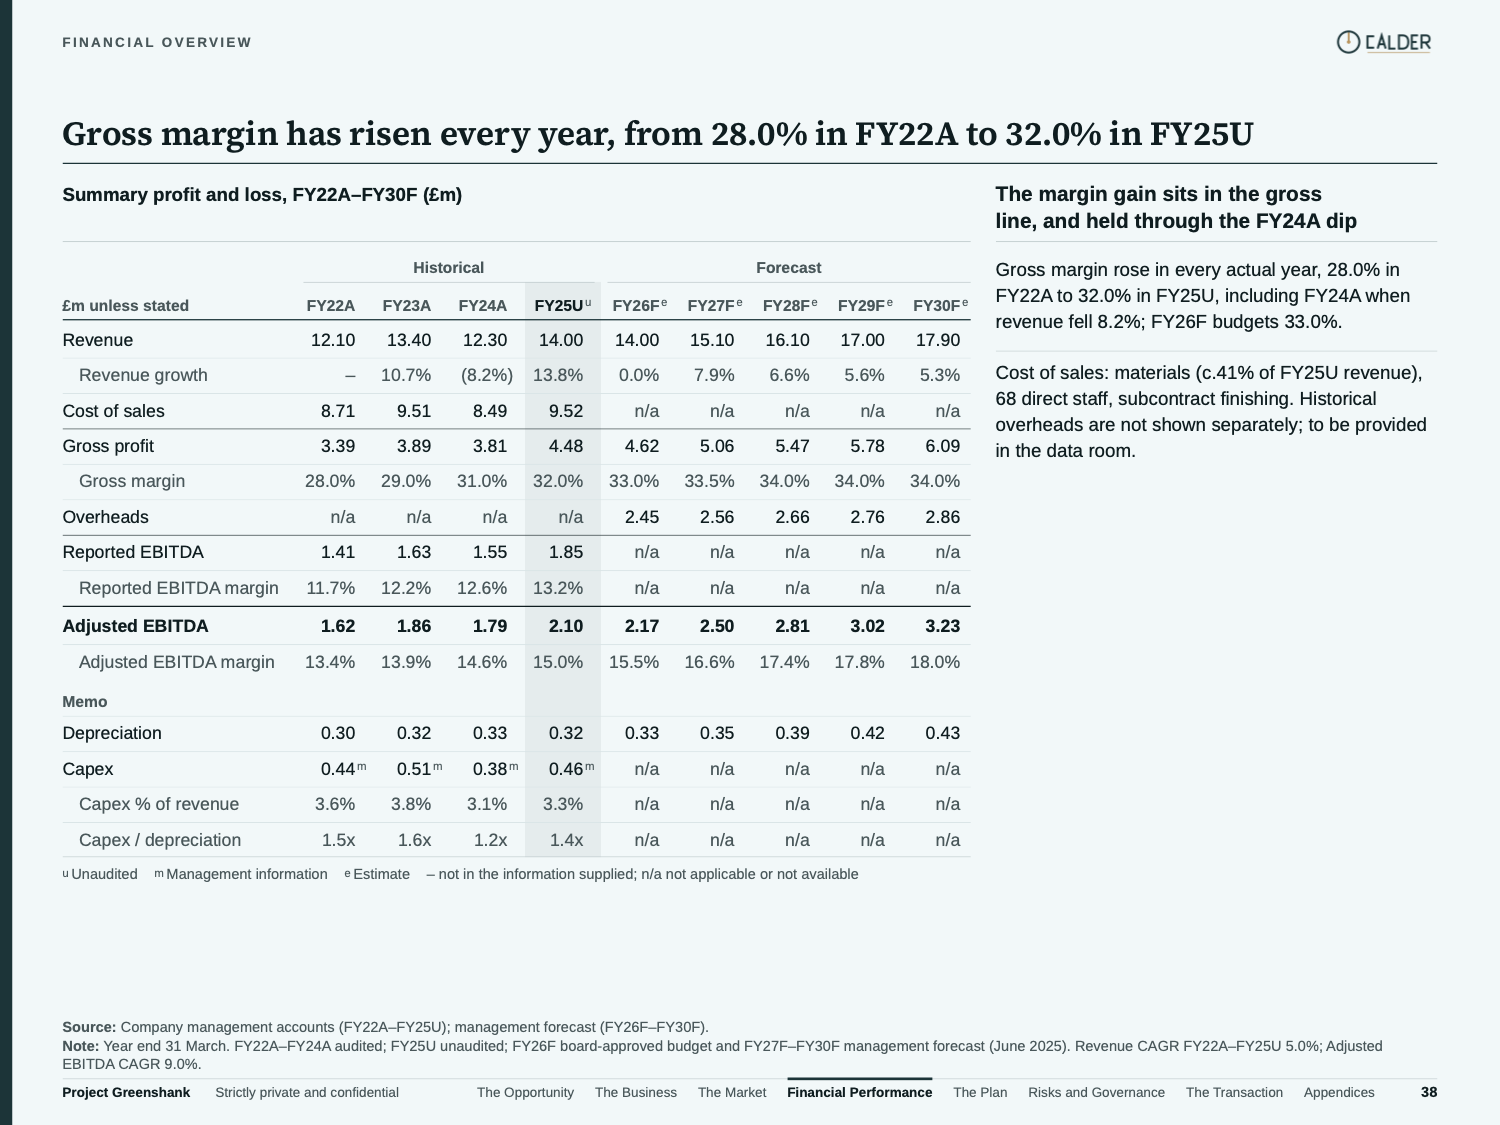
| £m | FY22 (Audited) | FY23 (Audited) | FY24 (Audited) | FY25 (Unaudited) | FY26 (Budget) | FY27 (Forecast) |
|---|---|---|---|---|---|---|
| Revenue | 12.1 | 13.4 | 12.3 | 14.0 | 14.0 | 15.1 |
| Revenue growth | — | 10.7% | (8.2%) | 13.8% | 0.0% | 7.9% |
| Gross profit | 3.4 | 3.9 | 3.8 | 4.5 | 4.6 | 5.1 |
| Gross margin | 28.0% | 29.0% | 31.0% | 32.0% | 33.0% | 33.5% |
| Adjusted EBITDA | 1.6 | 1.9 | 1.8 | 2.1 | 2.2 | 2.5 |
| Adjusted EBITDA margin | 13.4% | 13.9% | 14.6% | 15.0% | 15.5% | 16.6% |
| Reported EBITDA | 1.4 | 1.6 | 1.6 | 1.9 | — | — |
| Capex | 0.4 | 0.5 | 0.4 | 0.5 | 0.4 | 0.9 |
| Cash conversion | 88% | 86% | 92% | 89% | 99% | 92% |
£m; £ sterling unless otherwise stated.
FY25 refers to the year ended 31 March 2025; all years end 31 March.
The aggregate adjustment for each year is given in the footnotes.
Aggregate adjustments by year: FY22 £210k, FY23 £230k, FY24 £240k, FY25 £250k.
Each is the difference between the adjusted and reported figures in the table.
FY25 comprises shareholder remuneration above a market rate for a non-executive role, £185k (a market-rate Managing Director cost is retained), and rent above an independent market rent, £65k.
A full adjustment schedule is available under NDA.
Growth rates and margins are computed from unrounded figures.
Commentary
- FLAT FY26 BUDGET
- The FY26 budget includes none of the three initiatives' revenue; the FY27 forecast includes it. FY26 does carry £150k growth capex for the aftermarket cell fit-out.
- FY27 CAPEX STEP-UP
- £0.6m of FY27 capex is growth capex, buying the first additional 5-axis machining centre; non-growth capex is £294k in FY26 and £317k in FY27.
- CASH CONVERSION BASIS
- Cash conversion is (Adjusted EBITDA + working capital movement) / Adjusted EBITDA, before capex: 99% in the FY26 budget and 92% in the FY27 forecast.
FY26 budget cover
£14.0m, flat on FY25
- Contracted order book
- £9.1m · 65%
- Pipeline
- £3.6m · 26%
- Not yet identified
- £1.3m · 9%
Growth
| Initiative | Revenue at maturity | Investment | Timing | In plan | In FY26 budget |
|---|---|---|---|---|---|
| Aftermarket spares programmeSpares supply to existing OEM customers; two have requested it in writing. Revenue not in FY26 budget. | £1.2m | £150k | 18 months | Yes | No |
| Second shift at Site 2Adds a second shift at the site running at 61% utilisation; recruitment and training only, no capex. | £1.5m | £60k | 12 months | Yes | No |
| Two additional 5-axis machining centres at Site 2Quoted machines adding capacity once 22% group headroom is absorbed; first one carried in FY27 forecast capex. | £1.2m | £980k | 24 months | Yes | No |
| Total | £3.9m | £1.2m | |||
None of the three is in the FY26 budget; all three are in management's plan beyond it.
UPSIDE OUTSIDE THE PLAN
Management believes aftermarket spares can extend beyond the two OEM customers that have requested them, and European exports, £2.1m of FY25 revenue, can grow.
Sector metrics
- Capacity utilisation
- 78% overall, 22% headroom; Site 2 at 61%.
- Capex split
- FY25 total capex 3.3% of revenue; FY26 budget £294k non-growth (2.1% of revenue) and £150k growth.
- Active customers
- c.40.
Key considerations
Customer concentration
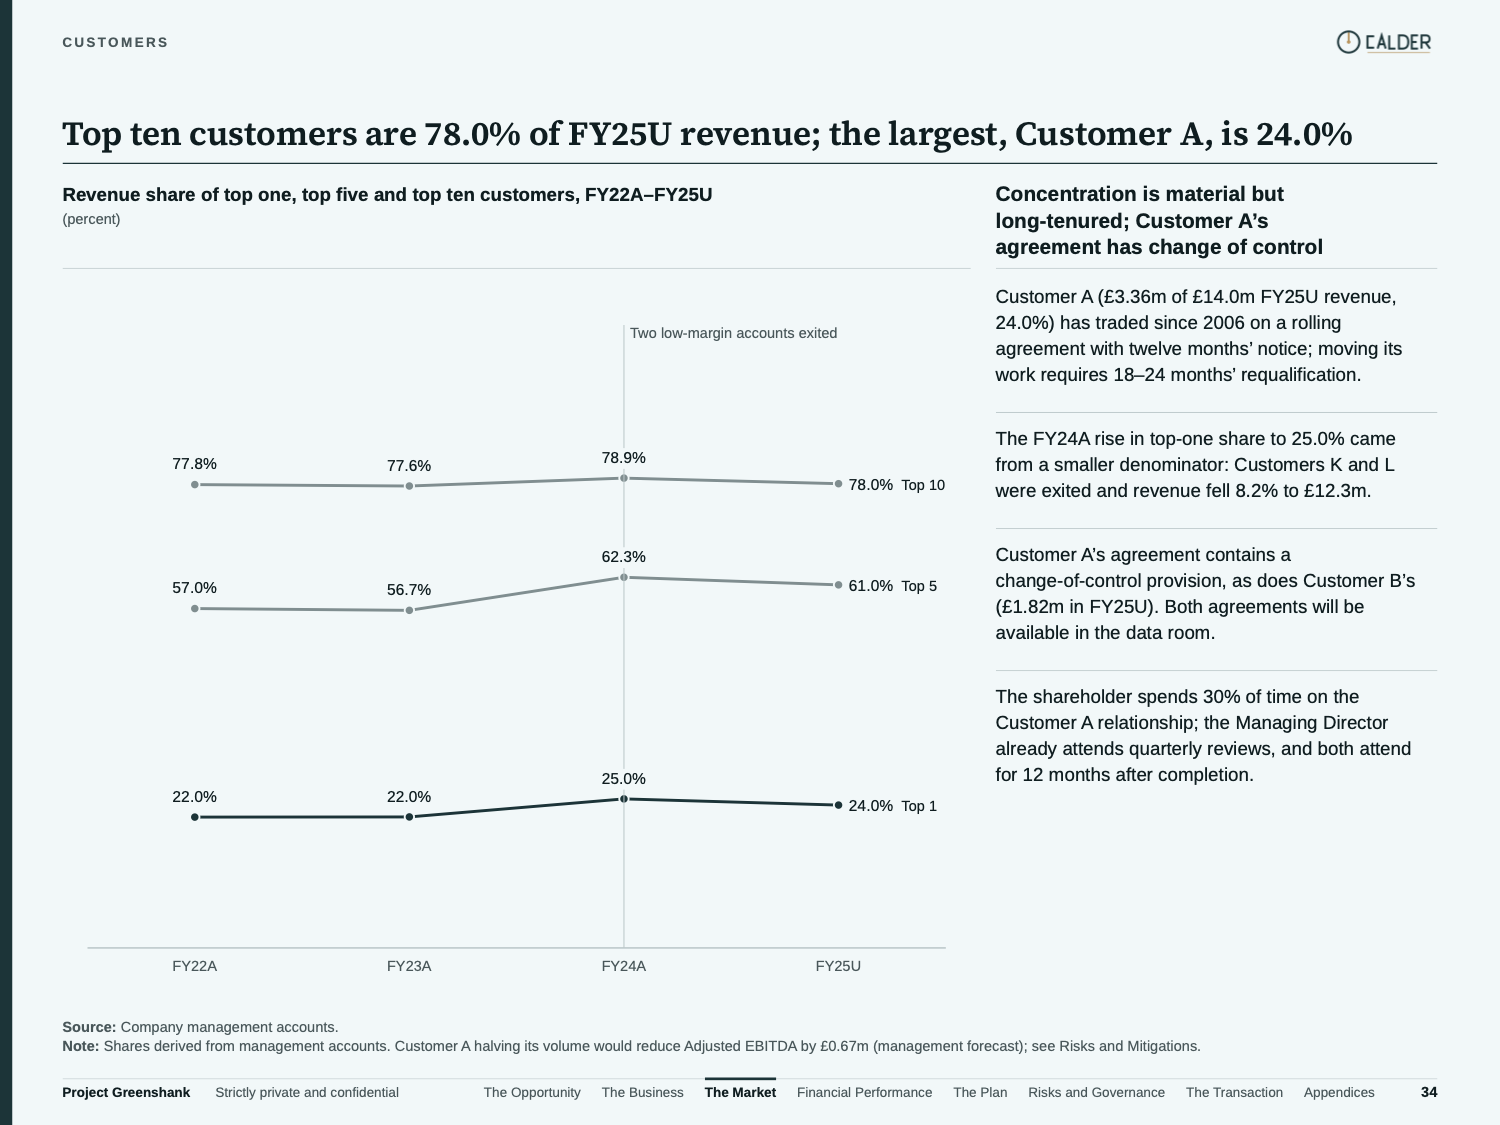
The top customer represents 24% of FY25 revenue and the top ten 78%, supplied under multi-year agreements on customer-owned tooling held on site.
Change-of-control clauses
Contracts carrying a change-of-control clause cover 37% of revenue; a customer moving that work would face 18–24 months of requalification and a physical transfer of tooling.
FY24 revenue decline
FY24 revenue fell 8.2% as £1.9m of customer revenue was lost, £1.6m through planned account exits; gross margin rose from 29% in FY23 to 31% in FY24, and revenue grew 13.8% in FY25.
Skilled machinist recruitment
Recruiting machinists for c.70 direct production roles is constrained regionally, and the second-shift initiative adds to that need; it carries £60k for recruitment and training.
Transaction
- REASON FOR SALE
- Shareholder retiring after over 30 years; no family succession.
- STRUCTURE
- 100% share sale, cash-free, debt-free, normalised working capital.
- MANAGEMENT
- Senior team, including MD, remains; shareholder is non-executive.
- HANDOVER
- 12-month handover.
- PROPERTY
- Both sites are freehold and both are in the sale; one may instead be leased back at independent market rent, which Adjusted EBITDA bears.
- CONSIDERATION
- Open to an element of deferred consideration.
- BUYERS INVITED
- Trade buyers and financial sponsors (private equity, family offices); UK and overseas
- WITH AN OFFER
- Evidence of funds; how the purchase is funded, set out with any offer
- WHY NOW
- The shareholder is retiring after more than 30 years with no family succession; the management team is in place and the contracted order book covers most of the budget year.
Bilateral, no fixed timetable; IM follows NDA. Interested parties are invited to contact the adviser to execute a non-disclosure agreement, following which a detailed Information Memorandum will be released. Contact: Marchmont Corporate Finance, Corporate Finance team, example@marchmontcf.example